BCH Price Analysis: Will BCH Bounce Back From This Shakeout?
Summary
The post BCH Price Analysis: Will BCH Bounce Back From This Shakeout? appeared first on Coinpedia Fintech News Failing to break above the $250 mark in the first few days of Uptober, the BCH price slides down the bearish alley. Moreover, the downtrend questions the spirit of Uptober this season as the overall market remains under acute selling pressure. The downtrend currently questions the possibility of a reversal for Bitcoin Cash and the BCH price prediction of reaching $300 in 2023. Taking a reversal from the overhead resistance zone at $250, also the neckline of the potential bullish pattern, the BCH price is down by 13%. Crashing under the 50-day EMA, the increasing selling spree brings Bitcoin Cash close to $200. Moreover, the recent sharp correction breaks the 38.20% Fibonacci level, where the buyers laid a consolidation range barrack to avoid further correction. With multiple bearish engulfing candles, the possibility of the BCH prices reaching the 200-day EMA is significantly higher. The BCH price is attempting to retest the 50-day EMA breakout and form a morning star pattern. Moreover, the altcoin is trading at $214.15 with no significant intraday move other than the 0.95% jump last night. Technical indicators: RSI indicator: The daily RSI line forms an arch to reverse from the overbought boundary to crack under the halfway line. Additionally, the RSI line fails to showcase any divergences to predict a reversal. EMA: The downtrend endangers positive alignment of the 50 and 200-day EMAs and warns of a death cross if prices slip under $180. However, the crucial support zone in confluence with the 200-day EMA will provide a cushion for a bullish revival. Will Bitcoin Cash (BCH) Price Crash Under $180? With the ongoing correction, the chances for a bullish revival among altcoins are slim but not zero. With crucial support zones nearby, the BCH price may soon form a solid footing to launch above the 50-day EMA. In such conditions, the reversal rally might rechallenge the $250 mark with eyes set on the $300 mark. On the flip side, if the price breaks below the $200 post, the downtrend will plunge the prices to $180.
As major retailers struggle to strike the balance between winning grocery delivery customers from competitors and boosting margins per order, Amazon conti…
Amazon Lowers Grocery Delivery Threshold as Retailers Tinker With Fees
Business Tools · Payments
Summary
As major retailers struggle to strike the balance between winning grocery delivery customers from competitors and boosting margins per order, Amazon continues to adjust its free delivery minimum for its Prime subscribers. The eCommerce giant announced Thursday (Oct. 5) that it has lowered the threshold for free grocery delivery for Prime members to $100, down from the previous minimum of $150, which itself was imposed earlier this year, a dramatic increase from the $35 threshold that was previously in effect. The move comes as major retailers weigh the challenges of making eGrocery more profitable versus winning the loyalty of customers amid stiff competition from rivals. Walmart, for its part, offers its Walmart+ members free grocery delivery on orders over $35, while non-members are charged between $7.95 and $9.95. Costco’s fees, meanwhile, vary depending on a number of factors, but the company’s same-day delivery option is only available for orders of $35 or more. Amazon’s move to lower its free delivery threshold for members comes as the company looks to grow its share of grocery sales — a category in which it lags far behind competitor Walmart. PYMNTS Intelligence finds that Walmart has captured a 19.3% share of consumers’ food and beverage spend — nearly eight times Amazon’s 2.6% share. In general, amid ongoing financial challenges, consumers have been loath to pay steep fees for delivery or to pay extra for the service. Take, for instance, restaurant ordering. PYMNTS Intelligence’s report “Connected Dining: Rising Costs Push Consumers Toward Pickup,” which drew from a survey of more than 2,100 U.S. consumers, revealed that 58% of takeout customers said they pick up restaurant meals to save on delivery fees, and 48% said inflation has made them more likely to choose pickup over delivery. Plus, high free delivery thresholds tend to limit online grocery’s audience. Indeed, PYMNTS Intelligence finds that eGrocery is highly skewed toward high earners. Last year’s study “The ConnectedEconomy Monthly Report: Paycheck-To-Paycheck Consumers Digitally Disengage” found that nearly half of all consumers earning $100,000 or more per year who do not live paycheck to paycheck had purchased groceries online in the previous month. Meanwhile, a far lower share of low-income consumers and those with no financial safety net had done the same. Still, grocery delivery adoption on the whole is on the rise. U.S. grocery giant Kroger, for its part, shared in a presentation shared with analysts last month accompanying its second quarter Fiscal 2023 financial results that its 12% year-over-year digital growth was driven in part by an uptick in delivery orders. Similarly, Albertsons shared in its most recent earnings report that its eCommerce sales rose 22% in Q1 FY2023. Grocery delivery is likely to continue to grow in the year ahead, as more consumers turn to digital channels. PYMNTS Intelligence’s report “Tracking the Digital Payments Takeover: Catching the Coming eCommerce Wave,” created in collaboration with Amazon Web Services (AWS), which drew from an April survey of nearly 2,700 U.S. consumers, revealed that 32% of shoppers said they are very or extremely likely to increase their online grocery purchases in the next year.The post Amazon Lowers Grocery Delivery Threshold as Retailers Tinker With Fees first appeared on PYMNTS.com.
Federal Reserve Gov. Christopher Waller said during a payments conference at the Brookings Institution Friday that the FedNow payments system has already …
Fed's Waller says FedNow adoption 'will grow over time'
Digital Currencies
Summary
Federal Reserve Gov. Christopher Waller said during a payments conference at the Brookings Institution Friday that the FedNow payments system has already enlisted "well over 100" depository institutions for the service and expects that number to grow.
Mastercard has launched new apprenticeships to help its employees learn new skills, improve career development opportunities, and support diversity across…
Mastercard offers digital and data apprenticeships to employees
Banking
Summary
Mastercard has launched new apprenticeships to help its employees learn new skills, improve career development opportunities, and support diversity across its business.
As the use of facial recognition software continues to expand around the world, concerns about privacy and human rights violations have reignited the deba…
Facial Recognition Debate Gathers Steam Despite Popularity Among Gen Z Consumers
Digital Currencies
Summary
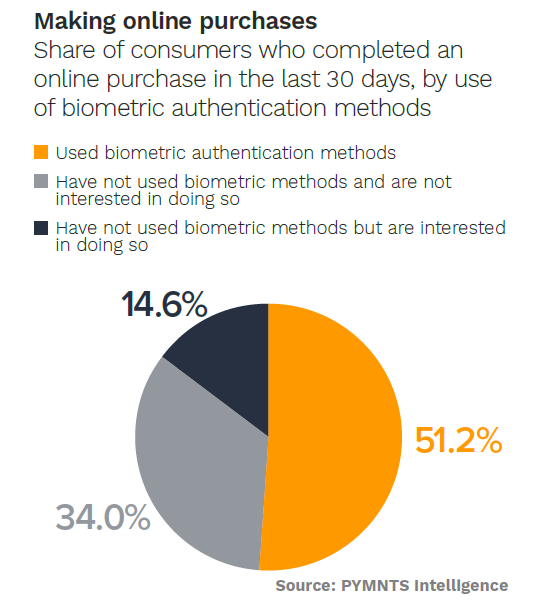
As the use of facial recognition software continues to expand around the world, concerns about privacy and human rights violations have reignited the debate surrounding this technology. On Friday (Oct. 6), a bipartisan group of 65 British lawmakers called for an immediate ban on live facial recognition surveillance on U.K. streets by both the police and private companies, Reuters reported. The use of the technology in the United Kingdom has faced consistent criticism from organizations advocating for civil liberties, including Amnesty International, and faces a proposed ban in the European Union under the EU’s landmark artificial intelligence (AI) regulation. On one hand, law enforcement officials have expressed optimism about the transformative potential of facial recognition technology in criminal investigations, but privacy advocates are concerned about privacy, human rights and the lack of sufficient regulation. The U.K.’s call for a ban on facial recognition comes at a time when other governments are taking steps to address concerns about biometrics. For example, China’s Cyberspace Administration (CAC) has introduced draft regulations calling for limits on facial recognition, proposing instead the use of non-biometric means to identify people. “The use of face recognition technology to process face information shall obtain the individual’s individual consent or obtain written consent in accordance with the law,” the proposal noted, per an Aug. 8 PYMNTS report. “If there are non-biometric verification technologies for achieving a similar purpose or business requirements, those non-biometric verification methods should be preferred.” In May, the Federal Trade Commission (FTC) issued a policy statement warning that the technology could lead to discrimination and violations of privacy. “In recent years, biometric surveillance has grown more sophisticated and pervasive, posing new threats to privacy and civil rights,” Samuel Levine, director of the FTC’s Bureau of Consumer Protection, said. “Today’s policy statement makes clear that companies must comply with the law regardless of the technology they are using.” Young Consumers Drive Biometric Adoption Meanwhile, most U.S. consumers seem unfazed by the intensifying debate surrounding AI facial recognition and continue to embrace biometrics tools as their most preferred way to authenticate payments. In fact, out of 60% of consumers who completed online purchases in a given period, 51% used biometric authentication to validate their transactions, eliminating the need to remember passwords or enter credit card information. This is one of the key findings in “Tracking the Digital Payments Takeover: Biometric Authentication in the Age of Mobile,” a PYMNTS Intelligence and AWS collaboration. The study also reveals that facial recognition and fingerprint scans are the most popular biometric methods, with approximately 28% and 49% of consumers, respectively, adopting them. Moreover, nearly 60% of facial recognition users use the method more than once weekly. Another interesting finding from the research is the contrast in biometric authentication adoption across different generations. While 84% of baby boomers and seniors have not used biometric authentication methods in the past 30 days, three out of four Gen Z and millennial consumers have incorporated biometrics into their routines. Among these younger generations, facial recognition is particularly popular among Gen Z consumers (51%) while millennials are more likely to prefer fingerprint scans, with 42.1% using them. Ultimately, the widespread adoption of biometric authentication tools by consumers signals a shift toward more convenient and secure payment methods. However, the balance between convenience and safeguarding individual rights and data will be a critical point of discussion in the evolving landscape of digital payments and biometrics. The coming years will likely bring further developments and changes as technology advances and society grapples with the implications of these innovations.The post Facial Recognition Debate Gathers Steam Despite Popularity Among Gen Z Consumers first appeared on PYMNTS.com.